PeakMetrics / Fact Checks
Economy & business fact checks
Explore claims publishers have checked about economy & business. Read their original ratings and follow the evidence.
Search fact checks
Search by text or image7,104 published reviews in this topic

Double taxation avoidance agreement signed with Mauritius, Cyprus, Singapore
Publisher’s rating: MISLEADING
The claim was part of an infographic about government actions to curb corruption. It described double taxation avoidance agreements as signed with Mauritius, Cyprus and Singapore, implying that all three were new agreements. FACTLY checked the Income Tax department’s list of agreements and examined the treaty wording and amendment history for each country. That evidence distinguishes the three cases. FACTLY reports that Mauritius and Singapore were already covered by agreements: the Mauritius agreement was later amended in August 2016, while the Singapore agreement had entered into force in 1994 and was amended in 2005, 2011 and 2017. Cyprus was different: the review quotes a notification stating that an agreement and protocol were signed in Nicosia on November 18, 2016. The review therefore finds that only Cyprus was a new agreement among the three countries named; the Mauritius and Singapore references concern older agreements and later amendments or protocols. Its conclusion is that presenting all three as newly signed agreements is misleading. The finding is specifically about whether these were new agreements, not whether India has tax agreements with those countries.
Black money (undisclosed foreign income and assets) and imposition of tax Act 2015 enacted.
Publisher’s rating: TRUE


వాహనదారులు టోల్ బూత్ కి 12 గంటల లోపు తిరిగి వస్తే వారికి టోల్ మినహాయింపు
Publisher’s rating: FALSE
వాహనదారులు టోల్ బూత్ కి 12 గంటల లోపు తిరిగి వస్తే వారికి టోల్ మినహాయింపు
Publisher’s rating: FALSE
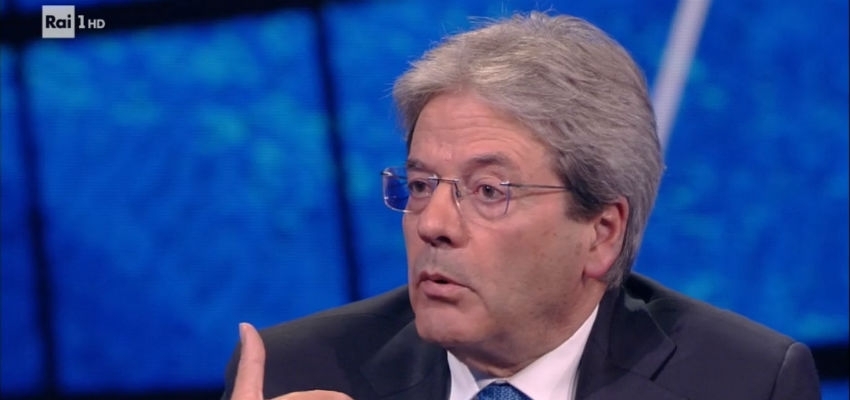
Il Governo cancella l’adeguamento all’inflazione delle pensioni basse. 3,4 miliardi tolti ai più bisognosi
Publisher’s rating: Nì

India’s GDP in current prices increased by 31% between 2013 and 2017 while the global GDP increased by 4%
Publisher’s rating: TRUE
FACTLY examined the claim about nominal GDP growth in India and worldwide from 2013 to 2017. It cites India’s National Accounts Statistics for domestic-currency figures: GDP at current prices was estimated at 105.4 lakh crore for 2013–14 and 151.8 lakh crore for 2016–17. The review also compares World Bank figures in current US dollars, which give India’s GDP as $1.857 trillion in 2013 and $2.601 trillion in 2017, and world GDP as $77.099 trillion and $80.738 trillion, respectively. Those World Bank figures imply growth of about 40% for India and 4.71% for the world. The domestic-currency figures cited by the review also show a rise, but from 105.4 to 151.8 lakh crore is about 44%, not 31%. Thus, the figures presented do not precisely substantiate the claim’s stated Indian increase; the review’s “TRUE” verdict rests on its assessment that the claim’s numbers are “more or less” similar to the calculated results. The review concludes that India’s GDP increased by 40% and world GDP by 4.71%, and says India’s growth was higher than the claim stated. Its evidence therefore supports the broad comparison that India’s nominal GDP grew more quickly than global GDP over the period, while also showing a notable gap between the claimed 31% and the review’s own 40% estimate.
India remains the world’s fastest growing large economy.
Publisher’s rating: TRUE
FACTLY checked the government infographic’s claim that India “remains the world’s fastest growing large economy” against the World Bank’s Global Economic Prospects report from January 2019. The review says the report estimated India’s growth at 7.3% for FY2018/19, and compared the report’s real-GDP-growth figures for India with those for other countries and the Emerging Market & Developing Economies group. It found India had the highest rate among large economies in the period examined. [S1: “The Global Economic Prospects report by the World Bank from January 2019 stated that ‘India’s growth accelerated to an estimated 7.3% in FY2018/19 (April to March) as economic activity continued to recover with strong domestic demand’.”; “The following table from the aforementioned report shows that the percentage change of real GDP from previous year is highest in case of India when compared to any other country’s economy and also highest among the Emerging Market & Developing Economies (EMDEs) for 2018-19.”] The review’s conclusion is specifically about the World Bank’s projections from 2018 onward. It notes that the report’s table placed India at the top for 2018 and 2019 and projected that position to continue. The review also says the World Bank categorized India as an emerging market and developing economy, while its growth rate was highest among the large economies. [S1: “The table also shows that India is set to retain the top position for the years of 2018, 2019 and further.”; “In the World Bank report, India is categorized under the category of Emerging Markets and Developing Economies. Further, the real GDP growth rate of India is highest of the large economies.”] The review includes an important qualification: India had not held the top position in 2016 and 2017, despite an earlier World Bank report having projected that it would. Thus, its conclusion relies on the newer projections and the specific period they covered; it should not be read as evidence that India had been the fastest-growing large economy in every prior year. [S1: “But that is the not case for 2016 and 2017.”; “This did not eventually happen.”]
India rated highly on all investment and macro-economic indicators.
Publisher’s rating: UNVERIFIED
The claim concerns whether India ranked highly across all investment and macro-economic indicators—not whether it performed well on any one measure. The review explains that the IMF, OECD and World Bank consider many indicators for international comparisons, and says establishing whether India ranks highly across all of them is difficult. It therefore treats the claim as unverified rather than establishing that India either did or did not rank highly overall. To show the breadth of the question, the review lists measures including GDP and sector growth, consumption, capital formation, savings, money supply, credit and deposits, fiscal deficits, inflation, trade, current-account and capital-account measures, foreign-exchange assets, external debt and the exchange rate. It points to OECD visualizations comparing gross fixed capital formation, World Bank visualizations of adjusted net national income growth, and IMF figures for real GDP growth. But those examples cover only selected measures; the review says there is no globally acceptable data for each indicator. Its stated basis for the UNVERIFIED conclusion is thus the difficulty of assessing the entire set consistently, not a demonstrated finding that India rated highly on all of them.

FEO act would also help the banks and other financial institutions to achieve higher recovery from fugitive economic offenders
Publisher’s rating: UNVERIFIED

Vehicular users would be exempted from paying toll charges at toll booths if they return in 12 hours.
Publisher’s rating: FALSE
The claim concerns a purported toll exemption for drivers who return to a toll booth within 12 hours. FACTLY describes it as a Facebook post and says the message had also circulated on WhatsApp and Facebook. The review reports that the claim was framed as an exemption applying to vehicular users on their return journey. To check the claim, FACTLY searched the National Highways Authority of India (NHAI) website for an official letter and looked for a public statement by Union Minister for Road Transport and Highways Nitin Gadkari. It reports finding no NHAI letter authorizing the exemption and no mention of such an exemption by Gadkari. The review also says that, when the same message circulated the previous year, India Today contacted Gadkari’s office, which denied that such an order or statement existed. On that evidence, the review concluded that the claimed 12-hour toll exemption was not supported by an official order or ministerial statement. The excerpt does not identify the particular toll booths or describe a specific journey; it evaluates the general claim circulated in the post.

El sector de la construcción se ha desplomado un 25%
Publisher’s rating: Falso
Benami Property act is aimed blocking a major avenue for generation and holding of black money in various forms.
Publisher’s rating: TRUE
The review examines a claim in a government infographic that the Benami Property Act is intended to block a major avenue for generating and holding black money. It explains that the 2016 amendment changed a law originally enacted in 1988, and describes a benami transaction as one in which property is bought in one person’s name using money provided by another, for the provider’s benefit. The review says the amendments provided for authorities to adjudicate cases and an appellate tribunal, and specified penalties for benami transactions. (S1: “A ‘Benami Transaction’ is one where a property is purchased in the name of an individual who has not paid for it.”; “The amendments passed by the BJP government seek to do the following. Amend the definition of benami transactions Establish adjudicating authorities and an Appellate Tribunal to deal with benami transactions Specify the penalty for entering into benami transactions”) For evidence of the law’s operation, the review cites a March 2017 Lok Sabha response. It reports that the earlier 1988 law had not been operational because of defects, while the amended law enabled specified authorities to provisionally attach benami properties that could later be confiscated. It also notes the potential criminal penalties described in that response. (S1: “a response in Lok Sabha in March 2017 stated that ‘though the Benami Transactions (Prohibition) Act, 1988 has been on the statute book since more than 28 years, the same could not be made operational because of certain inherent defects.”; “The amended law empowers the specified authorities to provisionally attach benami properties which can eventually be confiscated.”) The review’s principal quantitative evidence comes from a Lok Sabha response reporting figures through 31 December 2018: more than 2,000 benami transactions had been identified, provisional attachment had occurred in over 1,800 cases, and the value of attached properties exceeded Rs. 6,900 crore. These figures support the claim that the amended law addressed benami transactions; they do not, by themselves, measure how much black money was prevented or recovered. (S1: “till 31st December 2018, the IT department has identified more than 2000 benami transactions”; “provisional attachment of properties has been done in over 1800 cases and the value of properties under attachment is more than Rs. 6900 crores.”)
Ad seeking recruitment of rangers by the Kenya Wildlife Service
Publisher’s rating: False.

Claim by Facebook Page: 15 lac crore rupees of FDI in India due to PM Modi's foreign visits.
Publisher’s rating: Fact Crescendo rating: False.
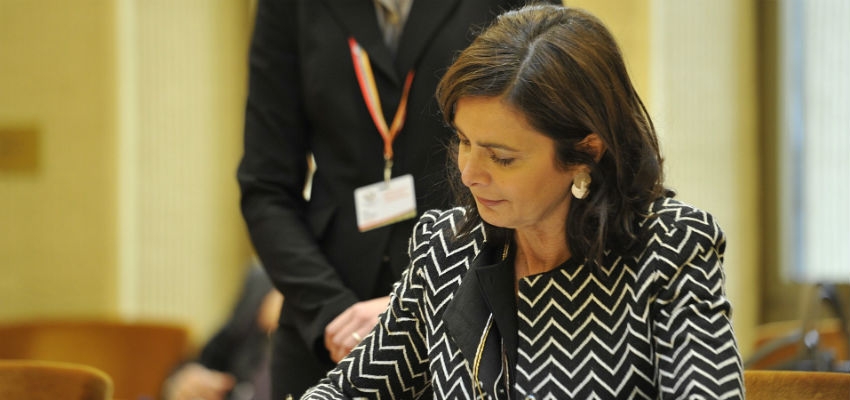

రఘురాం రాజన్: “ కాంగ్రెస్ ప్రభుత్వంలో ఉన్నప్పుడే రాహుల్ గాంధీ మరియు చిదంబరం కి నిరవ్ మోడీ యొక్క మోసాల గురించి హెచ్చరించాను. కానీ వాళ్ళు 2014 వరకు నన్ను మాట్లాడకుండా చేసి రుణాలు ఇప్పించారు. ఇప్పుడు పంజాబ్ నేషనల్ బ్యాంకు స్కామ్ లో నన్ను ఎందుకు నిందిస్తున్నారు?”
Publisher’s rating: FALSE
రఘురాం రాజన్: “ కాంగ్రెస్ ప్రభుత్వంలో ఉన్నప్పుడే రాహుల్ గాంధీ మరియు చిదంబరం కి నిరవ్ మోడీ యొక్క మోసాల గురించి హెచ్చరించాను. కానీ వాళ్ళు 2014 వరకు నన్ను మాట్లాడకుండా చేసి రుణాలు ఇప్పించారు. ఇప్పుడు పంజాబ్ నేషనల్ బ్యాంకు స్కామ్ లో నన్ను ఎందుకు నిందిస్తున్నారు?”
Publisher’s rating: FALSE